
- calendar_today August 7, 2025
Deductibles Increasing Across the State
Homeowners throughout Wisconsin are reporting insurance deductible increases, often without much advance notice. Deductibles, which represent the amount a policyholder must pay out of pocket before insurance coverage applies, are being raised in response to broader market dynamics, including inflation in construction materials and an uptick in severe weather events.
Previously, many policies carried flat-rate deductibles of $500 to $1,000. Now, insurers are increasingly shifting to percentage-based deductibles, often around 1–2% of the insured value of the home. This means that for a house insured at $300,000, a 2% deductible would equate to a $6,000 out-of-pocket cost before coverage kicks in.
This change can catch homeowners off guard, especially if they haven’t reviewed their policies recently. For families on tight budgets, the difference between a $1,000 and a $6,000 deductible can mean delaying critical repairs—or falling into debt.
Weather Events Are Driving Claims—and Deductibles
Wisconsin is no stranger to extreme weather. From blizzards and ice storms in the winter to heavy rains and wind in the summer, the state’s climate has always posed a challenge for homeowners. However, the frequency and intensity of these events appear to be increasing, and insurers are taking note.
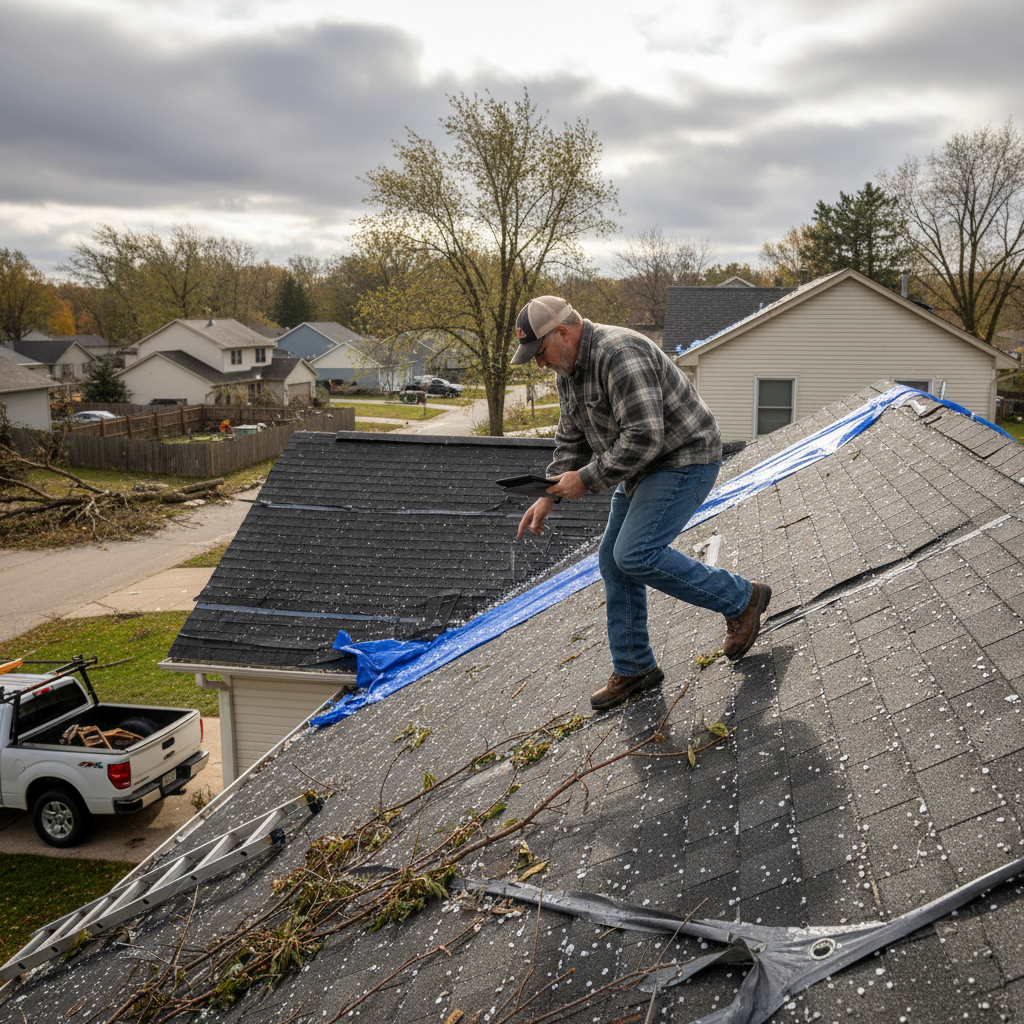
In recent years, damaging storms have led to thousands of claims across counties like Dane, Milwaukee, and Brown. Hail damage to roofs, flooded basements, and downed trees are common reasons for filing home insurance claims. As the number of claims rises, insurance companies are recalibrating their risk strategies—and raising deductibles is one of their primary tools.
Rising Repair Costs Make Matters Worse
In addition to higher deductibles, the actual cost of home repairs has increased significantly. Supply chain disruptions, labor shortages, and material inflation have all played a role in driving up expenses.
For example, replacing a damaged roof in Wisconsin might have cost around $8,000 a few years ago. Today, that figure can easily reach $12,000 or more. Combine that with a higher deductible, and homeowners are suddenly shouldering a much greater share of the repair cost burden.
Plumbers, electricians, and general contractors across the state report being booked weeks in advance—and charging more for emergency services. For those who cannot afford the upfront deductible, temporary fixes or partial repairs are becoming the unfortunate norm.
How Homeowners Are Responding
Faced with these realities, many Wisconsin homeowners are taking steps to better prepare for out-of-pocket costs. Emergency savings accounts, home maintenance checklists, and insurance reviews are becoming more common.
Home repair financing services are also seeing a rise in applications. Some homeowners are exploring personal loans or lines of credit to cover sudden expenses not fully paid by insurance. Others are shopping around for alternative insurance providers or adjusting coverage to secure more manageable deductibles, even if it means paying a slightly higher premium.
Local insurance agents are advising homeowners to schedule annual reviews of their policies. This includes checking current deductible amounts, understanding what types of damage are covered (and excluded), and considering supplemental coverage for common Wisconsin issues like sump pump failure or sewer backup.
Importance of Being Proactive
Experts recommend that Wisconsin homeowners take a proactive approach to both home maintenance and insurance planning. Simple actions like clearing gutters, inspecting roofs, and servicing HVAC systems can prevent costly damage and reduce the need to file a claim.
Documenting the condition of one’s home with photos and maintaining receipts for recent upgrades or repairs can also help streamline the claims process if damage does occur. Furthermore, knowing the full extent of one’s policy—especially what qualifies as a deductible event—is critical to avoiding surprises when it matters most.
Rural vs. Urban Homeowners: The Divide Widens
The impact of rising deductibles is being felt across the state, but there are notable differences between urban and rural homeowners. Residents in more rural counties like Sauk or Vernon often face higher premiums and fewer insurance provider options, making it more difficult to find competitive coverage.
Meanwhile, urban homeowners in Madison, Milwaukee, and Green Bay might have greater access to insurance brokers, roofing contractors, and financing options—but also face greater exposure to storm-related risks due to denser infrastructure and more frequent claims.
Regardless of geography, the trend is clear: higher deductibles are here to stay, and homeowners across Wisconsin need to adapt.
What’s Next for the Badger State?
While there’s no immediate sign of reversal, some industry analysts believe that stabilizing material costs and lower claim volumes in future seasons could ease deductible pressures over time. For now, however, Wisconsin homeowners are being urged to prepare for high upfront costs and stay vigilant in maintaining their homes.
The rising cost of being a homeowner isn’t just about mortgage payments anymore. With higher deductibles and climbing repair bills, financial planning and smart insurance decisions have become essential for weathering the next storm—literally and figuratively.




